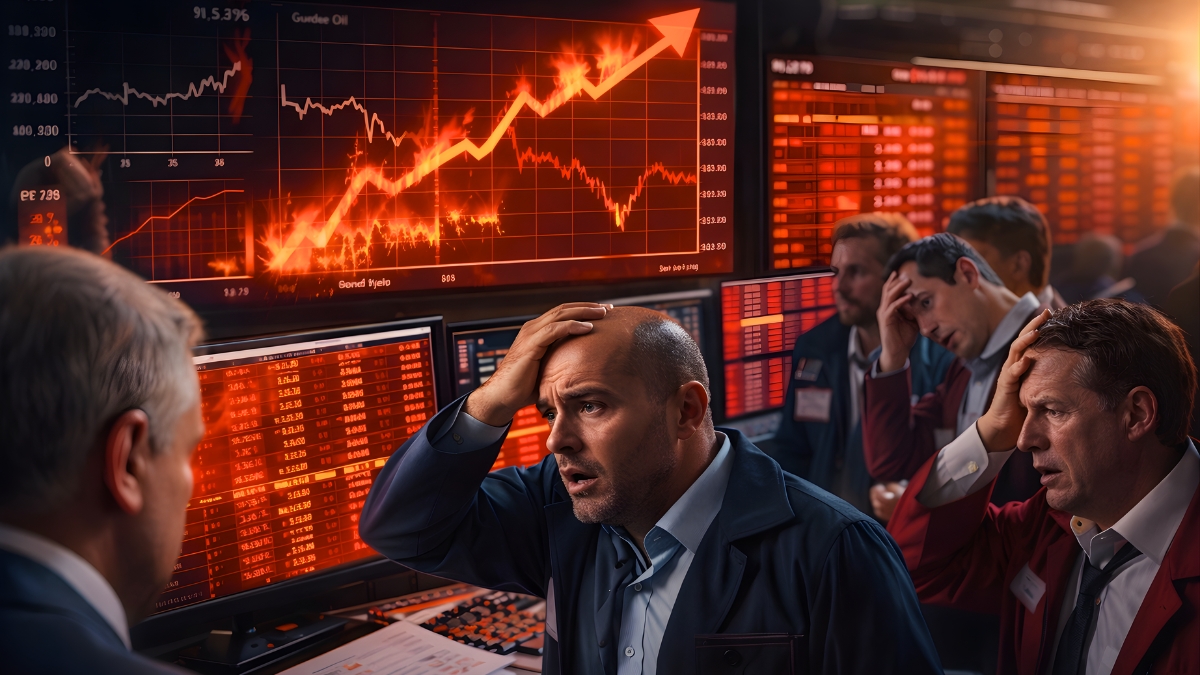
According to Yahoo Finance, investors entered 2026 expecting a friendlier backdrop for risk assets, with AI enthusiasm still strong, trade tensions looking more manageable than before, and hopes that lower interest rates could support stocks. Instead, the market has run into a pileup of problems at once. Oil prices have surged, inflation fears have returned, the Federal Reserve has become harder to read, Treasury yields have climbed, and equity leadership has cracked. By late March, the Nasdaq had confirmed a correction, the S&P 500 was under pressure, and investors were being forced to price in a world where growth is less secure and borrowing costs may stay elevated longer than many expected.
Quick takeaways
- The market is struggling because several major risks are hitting at the same time rather than one by one.
- Higher oil prices are raising fresh inflation worries just as investors were hoping price pressure would ease.
- The Fed is not in a clean position to cut rates aggressively if energy and tariff effects keep inflation sticky.
- Treasury yields have moved higher, which hurts valuations and tightens financial conditions.
- Growth fears are also building, making this look less like a healthy reset and more like a broad repricing of risk.
Why this selloff feels different
Markets can usually tolerate one problem at a time.
If growth slows but inflation cools, investors start betting on rate cuts. If inflation runs hot but earnings stay strong, stocks can sometimes push through it. If geopolitics worsen but energy stays calm, Wall Street often treats the shock as temporary noise.
What is making this moment feel more unsettling is that several of those cushions are failing at once.
Yahoo Finance framed the current mood bluntly: almost everything is going wrong for markets right now. That description lands because the problem is not just that stocks are down. It is that the usual offsets are weaker than investors expected. The same forces that are hurting sentiment are also complicating the policy response and undermining confidence in earnings, valuations, and consumer resilience.
In other words, the market is not only reacting to bad news. It is reacting to a shrinking number of easy bullish arguments.
Oil is back at the center of the story
One of the clearest reasons for the market’s discomfort is the jump in oil prices.
Reuters reported that the Middle East conflict has pushed crude sharply higher, with Brent settling above $112 a barrel and U.S. crude near $100 in late March. That matters far beyond the energy sector. Higher oil feeds directly into gasoline prices, shipping costs, industrial inputs, airline expenses, and inflation expectations. It also raises the risk that households pull back on discretionary spending just as consumer confidence is already wobbling.
When oil rises because demand is booming, markets can sometimes live with it. But when oil rises because supply is threatened and the global outlook is getting darker, the message changes. That kind of move behaves more like a tax on the rest of the economy.
This is why the latest market weakness has not been contained to a few speculative corners. Rising energy costs put pressure on both growth and inflation at the same time. That is one of the most difficult combinations for stocks because it hurts the economy while also limiting how aggressively central banks can respond.
The Fed no longer looks like a simple rescue story
Earlier in the year, many investors still hoped the Federal Reserve would be able to ease policy more comfortably in 2026. That story has become harder to defend.
After the March meeting, Fed Chair Jerome Powell said tariffs were still keeping inflation elevated and made clear that officials were also watching the impact of higher energy prices closely. He did not promise that the central bank could simply look through the latest oil shock. Instead, he emphasized uncertainty and the need for humility about how long price effects could take to pass through the economy.
That is a major issue for markets. Stocks often recover when investors think bad news will quickly force the Fed to step in with easier policy. But if inflation remains too sticky for comfort, the Fed has less room to cushion the blow. The market then has to absorb weaker growth without the same confidence in lower rates.
This is one reason the current pullback feels heavier than a normal profit-taking episode. It is not just about whether economic data softens. It is about whether softening data would even produce the policy support investors want.
Higher yields are squeezing valuations
Another part of the story is the bond market.
Reuters noted that U.S. Treasury yields have climbed to their highest levels since last summer as investors reassess inflation and interest-rate expectations. That matters because yields are the discount rate underneath modern equity valuations, especially for expensive growth stocks. When yields move up, the present value of future earnings comes down. That is particularly painful for technology and other long-duration assets that had benefited most from optimism around AI and lower-rate hopes.
This helps explain why market leadership has started to crack. The sectors that carried enthusiasm earlier in the cycle are the same ones that become most vulnerable when yields rise and investors get more selective. The market is not just falling; it is repricing the idea that the old winners can keep carrying everything.
That is also why the recent weakness matters psychologically. Once leadership breaks, investors stop asking only whether the dip is buyable. They start asking whether the narrative itself needs to be rewritten.
The correction in the Nasdaq is a warning sign, not just a headline
By March 26, Reuters reported that the Nasdaq had confirmed a correction, closing more than 10% below its prior record high. The S&P 500 and Dow also fell sharply, and the losses were broad enough to reinforce the idea that this was not just one bad day for a handful of stocks.
A correction does not automatically mean a bear market is next. But it does mean investor assumptions are being tested more seriously.
The important signal is not the round number alone. It is the breadth of the pressure behind it. Technology and communication services were among the weakest groups, chip stocks came under renewed pressure, and investors were rotating toward more defensive areas such as energy and utilities. That kind of internal market behavior usually says something deeper than simple exhaustion after a rally.
It says the market is trying to decide whether the world ahead looks less like a soft landing and more like a stagflation-lite environment in which growth slows, inflation stays annoying, and policy relief remains uncertain.
This is no longer only about geopolitics
It would be easy to write this whole selloff off as a geopolitical scare. That would be too narrow.
Geopolitics may have been the trigger, but markets are reacting so strongly because the shock is colliding with vulnerabilities that already existed. Inflation had not fully disappeared. Valuations in key parts of the market were still rich. Investors were already highly sensitive to any sign that rate cuts might be delayed. And confidence in perpetual AI-led upside had made the market more dependent on a relatively small set of leaders.
So when energy surged and the outlook darkened, the damage spread quickly. This is what turns a headline shock into a repricing event. It exposes how much optimism had been built on assumptions that now look fragile.
That fragility also shows up in the tone of the market conversation. Investors are not only worried about what happens next week. They are worried that the whole balance of 2026 may be shifting from disinflation-plus-growth to something much harder: slower activity, tighter financial conditions, and more volatile inflation.
Why consumer and business confidence matter here
Markets do not trade in isolation from the real economy.
Reuters reported that the conflict and the resulting rise in energy prices are beginning to sap both consumer and business confidence. That is crucial because equity valuations can survive plenty of noise when households keep spending and companies keep investing. But when confidence starts slipping, the effect can travel through the economy faster than many investors expect.
Higher fuel costs can crowd out other spending. Businesses facing uncertain demand and more expensive inputs may slow hiring or delay investment. Bond markets, seeing more inflation risk and more fiscal or geopolitical uncertainty, can demand higher yields. Each of those channels reinforces the others.
That feedback loop is why this moment feels so uncomfortable. The market is not simply dealing with one scary chart. It is dealing with the possibility that multiple charts start moving in the wrong direction together.
What could stabilize markets from here
The market does not need perfection to recover, but it does need one or two pressures to ease.
The cleanest relief valve would be a convincing de-escalation in the Middle East that brings oil down and lowers immediate inflation anxiety. Another would be evidence that higher energy costs are not feeding broadly into core inflation or consumer behavior. A third would be reassurance that earnings remain strong enough to justify current valuations even with rates staying higher for longer.
Without one of those offsets, rallies may remain fragile. Investors can handle uncertainty when they believe one major pillar is still solid. Right now, several pillars are wobbling at once, which is why every rebound attempt looks vulnerable to fresh selling.
What this means for U.S. readers
For Americans following the market from outside Wall Street, the bigger message is that this kind of selloff can spill into everyday financial conditions.
When markets fall because oil rises and rate-cut expectations fade, it is not just a story about portfolios. Mortgage rates can stay elevated. Credit conditions can tighten. Gasoline can eat more of the household budget. Retirement accounts can swing more violently. Business hiring plans can get more cautious.
That is why the phrase “almost everything is going wrong” resonates beyond traders. It captures a moment when the forces shaping markets are also shaping the cost of living and the economic mood.
The most important takeaway is not that panic is justified. It is that the current turbulence makes sense. Markets are reacting to a world where inflation risks, rate uncertainty, higher yields, expensive energy, and weaker confidence are all landing at once. Until at least one of those pressures breaks the other way, investors are likely to remain jumpy.
SOURCES
- Yahoo Finance — “Almost everything is going wrong for markets right now”
- Reuters — “Powell says tariffs keeping inflation elevated, Fed watching energy prices closely”
- Reuters — “Nasdaq confirms correction, Wall Street slumps on Middle East uncertainty”
- Reuters — “Stocks fall, oil prices rise on darkening economic outlook from Middle East war”
DISCLAIMER
General information only; not financial advice.