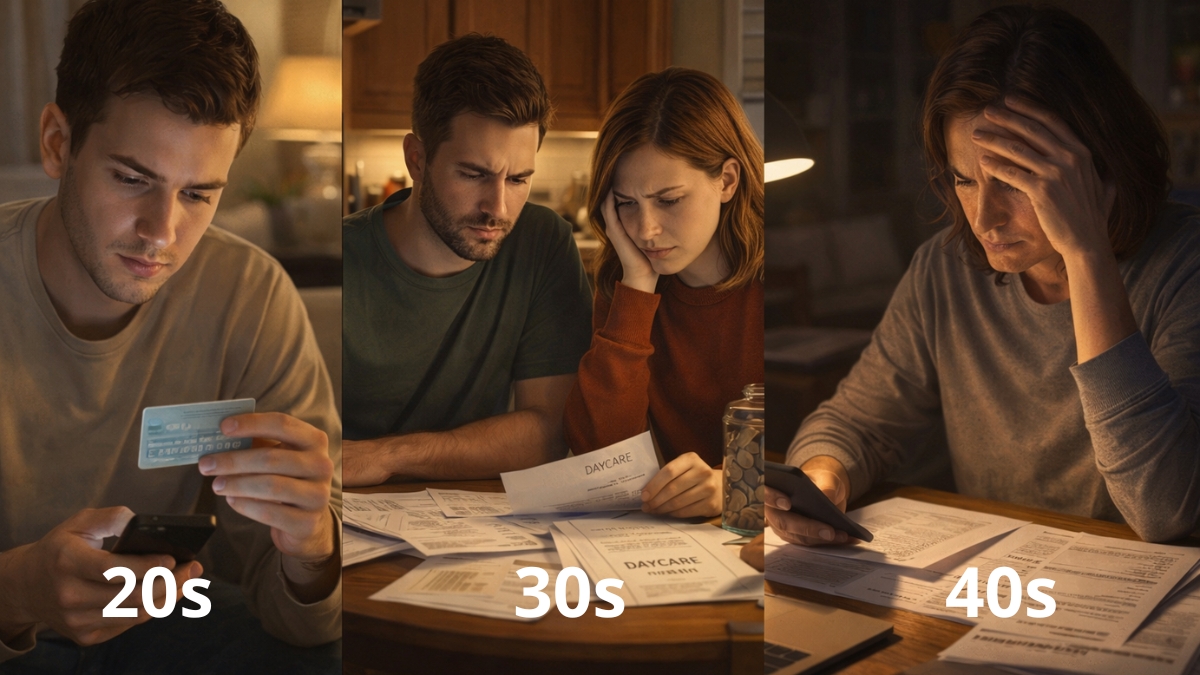
According to Bankrate’s 2025 Financial Regrets Survey, Americans’ most common money regrets are not saving for retirement early enough, taking on too much credit card debt, and failing to build enough emergency savings. Those regrets show up across every age group, but they do not feel the same in each decade of adult life. In your 20s, the pain usually comes from starting too late or borrowing too casually. In your 30s, it often comes from realizing that income growth did not automatically become wealth. In your 40s, regret gets sharper because the runway to retirement looks shorter, family obligations are heavier, and the cost of delay becomes harder to ignore. In 2026, that pattern feels even more intense because Americans are still living with the aftereffects of inflation, higher borrowing costs, and a household debt load that reached $18.8 trillion at the end of 2025.
Quick takeaways
- The biggest U.S. money regrets still center on retirement delay, credit card debt, and weak emergency savings.
- In your 20s, the most expensive mistake is usually not the first bad purchase but the habit of postponing saving and investing.
- In your 30s, regret often comes from discovering that bigger paychecks were absorbed by rent, childcare, debt, and lifestyle inflation.
- In your 40s, people feel the cost of delay more acutely because retirement math gets harsher and competing responsibilities pile up.
- In 2026, these regrets feel heavier because household debt is high, delinquencies have worsened slightly, and many Americans still do not have enough cash reserves.
The same regrets keep appearing for a reason
The striking thing about money regret in America is not that people make mistakes. It is that the same few mistakes repeat across age groups and business cycles.
Bankrate’s 2025 survey found that the top regret was not saving for retirement early enough, followed by taking on too much credit card debt and not saving enough for emergency expenses. That ranking makes sense because those three issues are tightly connected. When people delay saving, they lose time. When they carry expensive debt, interest compounds against them. When they lack emergency savings, even a modest setback can push them into borrowing at exactly the wrong moment.
In 2026, the broader backdrop makes those mistakes feel less theoretical. The New York Fed says total U.S. household debt hit $18.8 trillion at the end of 2025, with credit card balances up to $1.28 trillion and overall delinquency rates worsening slightly to 4.8%. That does not mean every household is in crisis, but it does mean more people are trying to fix old mistakes in a more punishing environment.
In your 20s, the biggest regret is usually waiting
People in their 20s often think the worst money mistake is buying something stupid. Sometimes it is. But the more durable regret is usually delay.
This is the decade when time is most powerful. A person who starts building an emergency fund, contributes to a 401(k), and avoids rolling credit card balances has an enormous advantage that may not look dramatic month to month but becomes huge over 10, 20, or 30 years. The problem is that your 20s rarely feel stable enough for long-term thinking. Entry-level pay is lower. Rent can consume a large share of income. Student debt may still be active. Social life is expensive. And many people assume they can get serious later.
That is why the regret pattern starts early. Bankrate’s emergency savings data show Gen Z adults were the most likely generation to have no emergency savings at all, and only a small minority had six months of expenses saved. The St. Louis Fed, citing the Federal Reserve’s 2024 household well-being survey, also showed that only 36% of adults ages 18 to 29 had savings set aside for three months of expenses. In other words, many young adults are not just behind on investing. They are financially exposed before they even begin.
The regret people describe later usually sounds like this: I thought I needed a higher salary before I could save. But that is often a framing error. In your 20s, the win is not perfection. It is building the first repeatable system: automatic transfers, some retirement contribution, and a habit of paying off high-interest debt quickly. The money can be small. The habit matters more.
Another classic regret in this decade is treating credit cards like income smoothing instead of short-term convenience. That can start innocently: travel, moving costs, furnishing an apartment, covering a deductible, replacing a laptop, saying yes to too many social expenses. The emotional trap is that nothing feels catastrophic. The financial trap is that APRs stay high while minimum payments make balances look manageable. Years later, people remember not the exact purchases but the feeling of having normalized revolving debt too early.
In your 30s, the regret becomes structural
Your 30s are often the decade when life gets more expensive faster than expected.
This is when many Americans move from individual money decisions to stacked obligations: rent or a mortgage, childcare, insurance, commuting, family logistics, helping parents, higher healthcare spending, and the subtle pressure to look established. Income may rise, but the number of things competing for that income rises too. That is why regret in your 30s often sounds less like “I bought the wrong thing” and more like “I let my whole cost structure get ahead of me.”
This decade is where lifestyle inflation becomes dangerous. A raise arrives, but so do bigger fixed costs. A larger home, a newer car, more subscriptions, more travel, more convenience spending, more child-related expenses, and less slack in the monthly budget. People tell themselves they are doing better because they earn more, yet their savings rate barely improves.
That gap between higher income and weak resilience shows up in the data. Bankrate found that millennials were the generation most likely to have tapped emergency savings in the previous 12 months, and 42% said they had done so. The Federal Reserve’s household well-being data also show a clear age gradient in financial resilience: while preparedness improves from the 20s into midlife, many adults still do not have enough cash to handle a prolonged interruption in income.
That is why one of the most painful 30s regrets is realizing that the emergency fund was never really an emergency fund. It was a pressure-release valve for regular life. Rent spikes, back-to-school costs, car repairs, seasonal travel, and medical bills keep punching holes in it. Then when a real emergency arrives, the household reaches for credit.
There is also a retirement version of this regret. In your 20s, retirement feels abstract. In your 30s, it becomes arithmetic. People begin to understand that “catching up later” is not a slogan but a costly promise. Northwestern Mutual’s 2025 study found Americans think they need $1.26 million to retire comfortably, and among those who have retirement savings, one in four say they have saved one year of income or less. The number is not important because everyone needs exactly $1.26 million. It matters because it captures the distance many households suddenly feel between what they have built and what they think they will need.
In your 40s, regret gets louder because time gets louder
By your 40s, financial regret changes tone. It is no longer just about whether a habit was imperfect. It is about whether there is still enough time to repair it without major sacrifice.
This is the decade when many households are simultaneously supporting children, carrying major housing costs, trying to protect aging parents, and confronting retirement planning with far less ambiguity. The issue is not simply that expenses are high. It is that choices begin to compete directly with the future. College savings may collide with retirement contributions. Mortgage payments may crowd out investing. Career disruption feels riskier because dependents are more likely. Healthcare and insurance suddenly matter more. And any debt carried into this stage feels heavier because it has lasted too long.
That pressure is visible in retirement sentiment. Northwestern Mutual’s 2025 study found Gen X respondents think they will need $1.57 million to retire comfortably, more than the national average, and more than half say they think it is likely they will outlive their savings. Nearly half expect to work during retirement or are already planning to do so, and many cite the need for additional income to afford retirement. This is not just abstract anxiety. It is the emotional shape of midlife regret: I earned, I worked, I tried to be responsible, and I still do not feel ahead.
Another 40s regret is more subtle: focusing too much on building assets and not enough on protecting them. Midlife households often become more vulnerable to concentrated risk. Too much wealth may be tied to a home, one employer, one business, or an expensive lifestyle that only works if income stays uninterrupted. Northwestern Mutual’s study found half of Gen X respondents said they had a financial blind spot by emphasizing wealth building without dedicating enough attention to protecting assets. That is a revealing kind of regret because it is not about irresponsibility. It is about imbalance.
Why these regrets feel more intense in 2026
This topic is not just timeless self-help. It is sharper in 2026 because the environment has made repair harder.
Household debt is higher. Credit card balances remain large. Delinquencies have worsened. Inflation is no longer at its peak, but many essential costs remain elevated relative to where they were before the inflation shock. Northwestern Mutual found inflation was still the dominant financial concern for 65% of U.S. adults in its 2025 study, and 44% called it the number one obstacle to achieving financial security. That matters because regret is usually most painful when people are trying to fix the past while the present is still expensive.
At the same time, emergency savings remain thin for a large share of the country. Bankrate’s 2026 Emergency Savings Report says only 46% of Americans have enough emergency savings to cover three months of expenses, while 24% have none at all. The Federal Reserve’s 2025 well-being report similarly found that in 2024, 55% of adults had savings set aside for three months of expenses, and 30% said they could not cover three months of expenses by any means. That is the real engine of regret. It is not just remembering a mistake. It is living in a system where one mistake can linger for years because there was never enough buffer to absorb it.
The real regret is not one purchase, but one pattern
When people look back on money mistakes, they often name a concrete object: the car, the vacation, the apartment, the shopping habit, the card balance, the delayed 401(k) signup. But the deeper regret is usually behavioral.
In your 20s, the pattern is postponement.
In your 30s, the pattern is expansion without protection.
In your 40s, the pattern is realizing that a decent income and a full life did not automatically create financial resilience.
That is why the same three regrets dominate survey after survey. They are not random categories. They are three versions of the same underlying problem: too little slack. Not enough time invested early. Not enough cash reserve when life gets expensive. Too much interest owed when something goes wrong.
What this means in the United States
For American readers, the practical takeaway is not that everyone should feel guilty about past decisions. It is that regret becomes useful only when it turns into diagnosis.
If someone in their 20s feels behind, the biggest win is usually to stop waiting for the perfect income and build an automatic system now. If someone in their 30s feels squeezed, the highest-value move is often not a dramatic reset but a ruthless look at recurring fixed costs and how often emergency savings are covering normal life. If someone in their 40s feels burned out, the key question is usually whether the household is finally prioritizing retirement and resilience ahead of status spending and legacy obligations that can expand without limit.
The emotional message of this topic is simple: Americans do not mainly regret wanting too much. They regret discovering too late that stability had to be built on purpose.
SOURCES
- Bankrate — “Survey: Nearly 3 In 4 Americans Have A Financial Regret”
- Bankrate — “Bankrate’s 2026 Annual Emergency Savings Report”
- Federal Reserve — “Report on the Economic Well-Being of U.S. Households in 2024: Savings and Investments”
- Federal Reserve Bank of New York — “Household Debt and Credit Report (2025 Q4)”
- Northwestern Mutual — “Planning & Progress Study 2025”
DISCLAIMER
General information only; not financial advice.