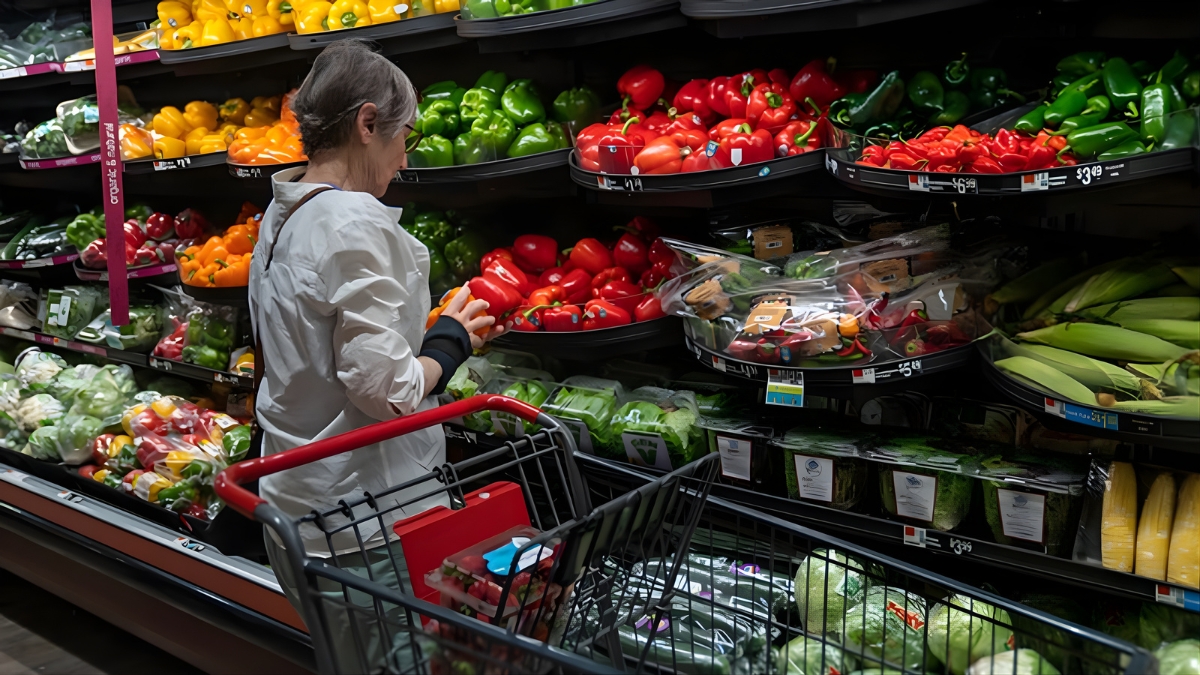
According to the U.S. Bureau of Labor Statistics, wholesale prices in the United States rose 0.7% in February from the prior month and were up 3.4% from a year earlier, a hotter reading than economists expected. The report landed on March 18, the same day financial markets were watching the Federal Reserve for clues on interest rates and the inflation path ahead. The February increase matters because producer prices often feed into what businesses charge consumers later. It also suggests that inflation is not fading as smoothly as policymakers, borrowers, and investors had hoped.
Quick takeaways
- U.S. producer prices rose 0.7% in February, above market forecasts.
- Annual wholesale inflation accelerated to 3.4%, the fastest pace in a year.
- Goods prices rose sharply, while services also continued to climb.
- The data complicates hopes for quick Federal Reserve rate cuts.
- Borrowers, savers, and investors now face a higher-for-longer inflation risk.
February’s producer price report was not just a routine data point. It was a reminder that inflation pressure can reappear in the pipeline even after months of slower progress.
The Producer Price Index, or PPI, tracks what businesses receive for their goods and services before those costs show up on store shelves or on monthly bills. That is why Wall Street and the Fed both watch it closely. A surprise rise in producer prices does not automatically guarantee faster consumer inflation, but it can be an early warning sign.
This latest report was strong in several places at once. BLS said final demand goods prices increased 1.1% in February, while final demand services rose 0.5%. The gauge that strips out foods, energy, and trade services also climbed 0.5% in the month and 3.5% over the past 12 months. That broad-based pattern makes the report harder to dismiss as a one-off spike in a single category.
What changed in February
A few details stand out.
First, the increase was faster than January’s 0.5% monthly gain. That means wholesale inflation has now posted a run of firm readings rather than a single hot month. Second, the annual rate moved up from 2.9% in January to 3.4% in February, matching the highest 12-month pace in a year. Third, price pressure was not limited to one side of the economy. Goods moved higher, but services kept rising too.
Reuters reported that the February gain was stronger than economists expected, which helps explain why markets reacted cautiously. Treasury yields moved higher and stocks opened under pressure as investors reassessed the odds of lower rates later this year.
That reaction is logical. When inflation data comes in hot, bond markets tend to price in a slower path to rate cuts. Companies may face higher financing costs for longer. Households can feel that through credit cards, auto loans, and mortgage rates, even if the Fed does not move immediately.
Why it matters for the Fed and for households
The Federal Reserve targets 2% inflation over time. PPI is not the Fed’s preferred inflation measure, but it feeds into the broader picture and can influence estimates for the Personal Consumption Expenditures index, or PCE, which the central bank follows closely.
In plain terms, this report makes it harder to argue that inflation is fully under control. If businesses continue to face higher input costs, some of that pressure can pass through to consumers. It may not happen evenly. Grocery categories, travel costs, housing-related services, and everyday household goods can all respond differently. But the general message is the same: relief on prices is proving uneven.
For households, that matters right away. Higher inflation can keep borrowing costs elevated, squeeze real wage gains, and make it more expensive to carry variable-rate debt. People waiting for cheaper refinancing or lower credit card pressure may have to wait longer.
For businesses, especially smaller firms, the issue is margin pressure. They either absorb rising costs or try to pass them along. Neither choice is painless in a consumer economy that still looks price sensitive.
What the market is watching next
The next question is not whether February was hot. It was. The more important question is whether this was the start of a fresh inflation leg or a temporary burst that cools in the next few reports.
Investors will now watch several things. One is the next consumer inflation and PCE readings to see whether producer-price pressure is flowing downstream. Another is the Fed’s language around inflation risks and rate timing. A third is whether energy, food, and transportation costs stay elevated, because those categories can quickly shape inflation expectations.
The BLS release schedule shows the March 2026 PPI report is due on April 14. That gives markets less than a month to decide whether February was noise or a warning. Until then, each major inflation print is likely to carry extra weight.
There is also a confidence issue. Inflation does not need to surge back to earlier peaks to change behavior. If businesses and households start to expect prices to stay sticky, they may make more defensive decisions, from delaying purchases to demanding higher wages or keeping price hikes in place longer.
What this means in the US
For U.S. readers, the practical takeaway is simple: hopes for fast, broad price relief may be premature.
A hotter PPI reading does not guarantee a new inflation spiral, and one month never tells the whole story. But it does argue for caution. Rate-sensitive products may stay expensive. Monthly budgets may remain tight. Market volatility can also rise when investors are forced to rethink the outlook for inflation and Fed policy in the same week.
That makes this report more than a data headline. It is a signal that the inflation fight still has friction in the system, even this late in the cycle.
What consumers can do now
There is no need for panic, but this is a reasonable moment for a household check-in.
Review variable-rate debt first. Credit card balances and adjustable borrowing are usually the most exposed when rate relief gets pushed out. Next, revisit recurring expenses that have already moved higher over the past year, including food, utilities, and insurance. Finally, avoid building a budget around imminent rate cuts or sharp price relief until more inflation data confirms that trend.
That is not a forecast of another inflation surge. It is simply a reminder that sticky inflation tends to punish optimism that arrives too early.
SOURCES
- Bureau of Labor Statistics — “Producer Price Index News Release: February 2026”
- Bureau of Labor Statistics — “Schedule of Releases for the Producer Price Index”
- Reuters — “US producer prices surge in February on services”
- Associated Press — “US wholesale prices rose by a surprisingly hot 3.4% last month”
- CNBC — “Wholesale prices rose 0.7% in February, much more than expected and up 3.4% annually”
DISCLAIMER
General information only; not financial advice.